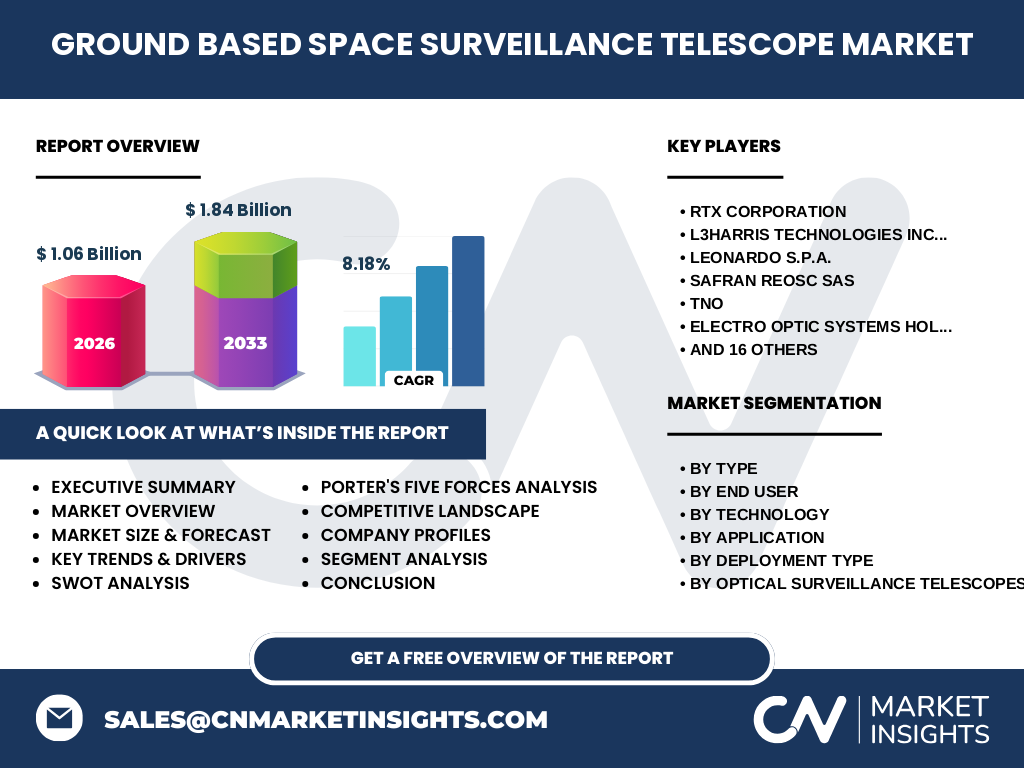
What is the market overview of the Ground-Based Space Surveillance Telescope Market?
Our analysis indicates that the Ground-Based Space Surveillance Telescope Market is valued at $1.06 Billion in 2026, serving as a critical infrastructure pillar for orbital defense and commercial space traffic management. Driven by escalating orbital congestion, this sector encompasses specialized optical, infrared, and hybrid tracking hardware utilized by sovereign defense ministries and commercial operators to safeguard high-value space assets.
Structural Growth Drivers and Market Restraints
Growth is aggressively propelled by rising Low Earth Orbit satellite constellations and stringent mandates from regulatory bodies like the UN Office for Outer Space Affairs. However, industry expansion faces severe physical and logistical restraints, notably severe atmospheric distortion, high optical-grade glass procurement hurdles, and stringent sovereign export controls governing advanced tracking wavelengths.
The Shift Toward AI-Enabled Tracking Systems
The market is witnessing a profound architectural shift toward Artificial Intelligence Enabled Tracking Systems and Adaptive Optics to overcome atmospheric seeing limitations. Industry innovators like Slingshot Aerospace Inc. and Neuraspace Lda are integrating proprietary algorithms with hardware platforms from manufacturers like Officina Stellare S.p.A. to automate conjunction assessment and drastically reduce false-positive collision alerts.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains for zero-expansion glass ceramics and precision optical coatings, delaying major astronomical observatory upgrades across Chile and the Canary Islands. Recovery has been robustly catalyzed by accelerated national security budgets, pushing the market toward a stellar CAGR of 8.18% as space-faring nations prioritize domestic orbital surveillance resilience.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a distinct bifurcation between entrenched aerospace primes such as RTX Corporation, L3Harris Technologies Inc., and Leonardo S.p.A., and agile pure-play space domain awareness startups like Spaceflux Ltd. and Digantara Research and Technologies Private Limited. Strategic positioning increasingly hinges on turnkey software-hardware integration and rapid deployment capabilities.
Executive Summary: Ground-Based Space Surveillance Telescope Market
Synthesizing our exhaustive market research, the Ground-Based Space Surveillance Telescope Market represents a high-barrier, technology-intensive sector set for rapid commercial and defense expansion. Key findings reveal that shifting from manual observation to autonomous, AI-driven optical networks will unlock unprecedented commercial scalability for global operators navigating increasingly hazardous orbital pathways.
Market Forecast and Revenue Trajectory
Our proprietary financial modeling projects the market to expand from $1.06 Billion in 2026 to reach $1.84 Billion by 2033, expanding at a steady CAGR of 8.18%. This sustained upward trajectory is fueled by sustained defense procurement cycles and the burgeoning commercial imperative for dedicated space situational awareness services.
Segmentation Analysis across Key Operational Vectors
The market is comprehensively segmented by Type (Optical, Infrared, Electro-Optical, and Hybrid systems), End User (Defense and Space Agencies, Government Research, Commercial Operators, Academic Institutions), Technology (Passive/Active Optical, Adaptive Optics, AI Tracking), Application (Debris Tracking, Satellite Monitoring, SSA, Missile Warning), and Deployment (Fixed Installations, Mobile Systems).
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily concentrated in North America and Europe, supported by legacy defense installations and dense clusters of specialized optical manufacturers like Safran Reosc SAS and ASA Astrosysteme GmbH. Meanwhile, the Asia-Pacific region exhibits the fastest relative growth, spurred by national space programs led by entities such as ISRO expanding domestic tracking apertures.
In-Depth Regional Review of Strategic Infrastructure
North America dominates demand through heavy Pentagon investments in deep-space tracking fences, while European markets leverage collaborative frameworks via the European Space Agency. In the Southern Hemisphere, optimal viewing conditions in the Atacama Desert in Chile and the Karoo in South Africa make regions anchored by EOS Space Systems (Pty) Ltd prime operational hubs for global surveillance networks.
Company Profiles and Strategic Positioning
Leading industry participants leverage distinct core competencies to capture market share. TNO and SENER Aeroespacial S.A. excel in custom adaptive optics engineering, whereas PlaneWave Instruments Inc. and ASTELCO Systems GmbH dominate the commercial-grade robotic telescope segment, providing cost-effective apertures for emerging commercial space tracking constellations.
Porter's Five Forces Analysis of the Industry
Our analysis indicates moderate-to-high threat of new entrants constrained by extreme capital requirements and specialized optical engineering expertise. Bargaining power of buyers is high among sovereign defense agencies demanding bespoke architectures, while the threat of substitutes remains exceptionally low due to the irreplaceable physics of ground-based photon collection.
SWOT Analysis of the Surveillance Ecosystem
Strengths include mature optical manufacturing techniques and vital strategic defense necessity. Weaknesses involve high maintenance overheads for remote mountaintop installations. Opportunities lie in commercial debris tracking contracts, while threats encompass geopolitical supply chain disruptions for rare-earth optical dopants and space-based SSA alternatives.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing ultra-low expansion glass ceramics, progressing through precision optical grinding and coating houses like Safran Reosc SAS, hardware integration by primes like Kratos Defense & Security Solutions, and culminating in data-as-a-service analytics delivered to commercial satellite operators and defense commands.
Investment Insights and High-Potential Areas
High-potential investment avenues center on Autonomous Hybrid Tracking Systems and software platforms capable of fusing optical data with radar inputs. Venture capital and defense funds should prioritize firms offering scalable, AI-driven data processing pipelines that reduce the human analyst bottleneck in space traffic management.
Conclusion and Strategic Takeaways
The Ground-Based Space Surveillance Telescope Market offers compelling long-term fundamentals anchored by an expanding $1.84 Billion by 2033 valuation. Stakeholders must prioritize software-defined hardware agility and strategic partnerships with commercial SSA providers to successfully capture high-margin government and enterprise contracts.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with aerospace chief technology officers, customs trade registry data on optical component shipments, and secondary macroeconomic indicators from international space agencies to ensure robust, actionable market sizing.
Scope of the Report and Coverage Parameters
This comprehensive report covers global deployment models, commercial pricing trends, and technological roadmaps from 2026 through 2033. Excluded from this specific scope are space-based optical surveillance payloads, focusing strictly on ground-based infrastructure, fixed installations, and mobile terrestrial tracking assets.
Recent Developments and Industry Announcements
Recent market dynamism is highlighted by Hensoldt securing defense contracts for advanced electro-optical tracking sensors, alongside strategic cross-border partnerships between software innovators like Sybilla Technologies Sp. z o. o. and hardware manufacturers to deploy turnkey, network-centric optical surveillance nodes across multiple continents.